Short answer: it depends on how the water got in. Most homeowners policies cover water damage that is sudden and accidental, such as a supply line that snaps or a pipe that bursts inside a wall. They often do not cover damage from a leak that dripped for months, and they do not cover flood.
The question carries real weight in Manhattan Beach, where homes sit among ocean exposure, steep hillsides and busy boulevards. According to the California Department of Insurance, standard homeowners policies leave out flood damage yet respond to other kinds of water damage. Below is how that split works and what to do on day one so your claim starts with a clean record.
Sudden and accidental versus gradual
Insurers read a loss for its cause. A washing machine hose that splits at 2 a.m. and floods a laundry room is a sudden event. A toilet seal that has wept into the subfloor for a year is a gradual one, and policies often treat that as maintenance rather than a covered loss.
Your own policy wording decides the outcome, so read the section on water, plumbing and seepage before you assume anything. If a phrase confuses you, ask your insurer to explain it in writing. Nobody can tell you in advance how a claim will turn out, and we do not predict approvals.
A quick sorting table
Use this table as a starting point for the conversation with your insurer. It describes how these situations are commonly treated, not a promise about your policy.
| Situation | Commonly treated as | What to do first |
|---|---|---|
| Pipe bursts inside a wall overnight | Sudden and accidental, often covered | Shut off the main valve, photograph everything, call your insurer |
| Dishwasher or washer hose fails | Sudden, often covered | Stop the water, keep the failed part, document wet materials |
| Slow leak under a sink for months | Gradual, often not covered | Fix the source and dry the area, then ask about your options |
| Roof leak after a heavy rain | Depends on the policy wording | Tarp or cover the opening and keep the receipt |
| Rising water from outside, storm surge or runoff | Flood, excluded from homeowners policies | Check for a separate flood policy |
| Sewage backing up through a drain | Depends on endorsements | Stay out of the water and read your policy for backup coverage |
Notice that the last row says depends. Sewer and drain backup is often an optional add-on, so a policy that handles a burst pipe may still say nothing about a backed-up line.
Water still moving through the house?
Call the 24/7 line. Same-day response is available when crews are available.
Flood is a different policy
The Department of Insurance guide states that flood coverage can be bought as a separate policy. Water that enters from outside and rises across the ground is flood, even if the same storm also damages your roof.
Not sure which side your address falls on? Pull up the FEMA flood map and read your policy's declarations page next to it. If floodwater has reached your floors, the cleanup follows the urgent steps on our flood damage restoration page, whatever the coverage answer turns out to be.
What to document in the first day
Good records make every later conversation easier. The state guide suggests keeping a log of phone calls and correspondence and copying everything you send or receive. Write down who you spoke with and when.
Photograph the damage before anything moves, then list damaged items with brand names and model numbers where you can. Do not throw out damaged belongings until the adjuster tells you to. That includes soaked carpet padding, wet furniture and ruined appliances.
Stop the source
Close the fixture valve or the main water shutoff so the loss does not grow.
Photograph and film
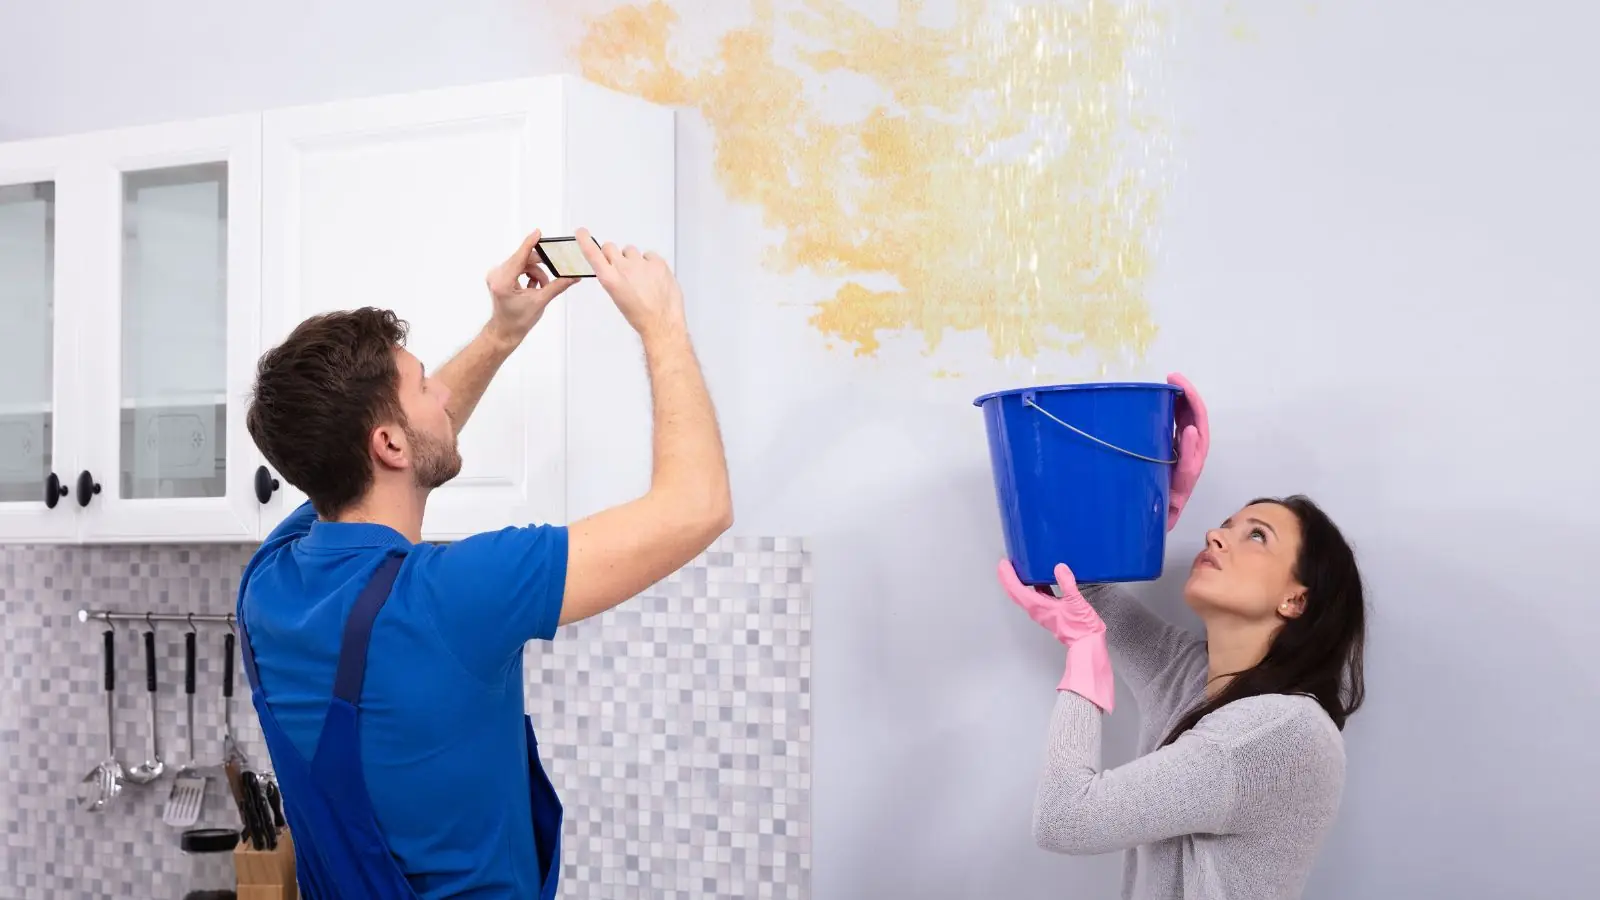
Capture wide shots of each room, then close shots of stained walls, ceilings and floors.
Call your insurer
Report the loss, ask what they need, and write down the claim number.
Protect the property
Cover openings, move valuables and begin drying. Keep every receipt.
Keep the evidence
Keep failed parts and damaged belongings until the adjuster says they can go.
Protecting the home is part of your job
Policies may not cover ensuing damage if you did not take reasonable steps to protect the property. The same guide says your insurer will reimburse reasonable costs to protect your property, as long as you keep receipts.
In practice that means temporary measures are expected. Extraction, tarping and drying equipment started early can keep a small loss from becoming a larger one, which is why our water damage cleanup work begins with stopping spread and recording what was wet. Avoid extensive permanent repairs until the adjuster has inspected, because they may need to see the original condition.
Living elsewhere while the home dries
If the house is unsafe to live in, the guide notes that additional living expenses may apply under some policies. Keep receipts for temporary housing, food costs above your normal spending and similar items.
Ask your insurer in your first call what documentation they want for those costs. Policies differ, so treat any figure you hear from a neighbor as irrelevant to your own coverage.
Why drying speed matters to a claim
Moisture left alone keeps spreading. A loss that sits wet for a week is harder to scope, and mold can end up on the list of problems to resolve.
The state guide says the same thing in its own words: dry wet areas promptly to reduce mold risk. Moisture readings taken on day one and again as drying progresses give you an objective record of what happened and when.
How we fit into your claim
We are restoration professionals, not your insurer or your adjuster. We explain scope and price before work starts, record moisture readings and affected areas, and give you documentation you can pass along. We do not promise any claim outcome.
A note for Manhattan Beach homeowners
Manhattan Beach's Fire Department posts a Natural Hazards Mitigation Plan on its emergency plans page. It names floods, earthquakes, landslides and tsunamis among the hazards that can touch the city, and it points to a possible tsunami inundation area map. It does not offer a flood zone lookup for individual addresses.
So the practical move is to look your property up on the FEMA flood map and then ask your insurer plainly whether the policy includes flood coverage. Repair permit questions go to the city's Community Development office, 1400 Highland Avenue, because rules differ from city to city.
Neighbors in Redondo Beach and Lawndale face the same split between flood and other water, and we serve both from Manhattan Beach. The questions to ask your insurer are identical on either side of the city line.
Questions about does homeowners insurance cover water damage in manhattan beach?
Does homeowners insurance cover a burst pipe in Manhattan Beach?
Many policies cover the damage a sudden pipe break causes, though the details vary by policy. Some pay for the resulting damage but not for repairing the pipe itself. Read the water damage section of your policy or ask your insurer which parts apply.
Is a slow leak covered?
Often not. Gradual seepage and long-term neglect are commonly excluded because the loss builds up over time. Fixing the source and drying the area quickly still protects the rest of the house.
Do I need separate flood insurance near the beach?
The state's consumer guide says homeowners policies exclude flood, and that flood coverage is purchased on its own. Look up your property on the FEMA flood map and ask your insurer or agent what fits your situation.
Should I start drying before the adjuster arrives?
Reasonable protective steps are expected, and your insurer should reimburse reasonable costs when you keep receipts. Photograph first, remove standing water, and avoid large permanent repairs until the adjuster has looked.
Can restoration records help my claim?
Moisture readings, affected-area notes and photos can give an adjuster a clear picture. We provide them on request, though the claim decision always rests with your insurer.